
Summary
- The company has launched two products, DEXYCU and YUTIQ. Both have very substantial market potential, and orders are ramping fast.
- Due to a situation with its distributor, the ramp in orders hasn't translated into an acceleration in revenue. Quite the contrary, in fact.
- This disconnect between orders and revenue is clouding the assessment on how fast revenue could ramp and how much new capital the company is going to need.
- This is holding the shares down, but we still think there is a very good opportunity here given the potential market size and margin profile, though only for risk-tolerant investors.
We wrote in August that EyePoint Pharmaceuticals (EYPT) had two big market opportunities with their products, but after a subsequent rally that doubled the stock price, investors have since cooled on the stock in response to Q3 figures and we're almost back to where we started:
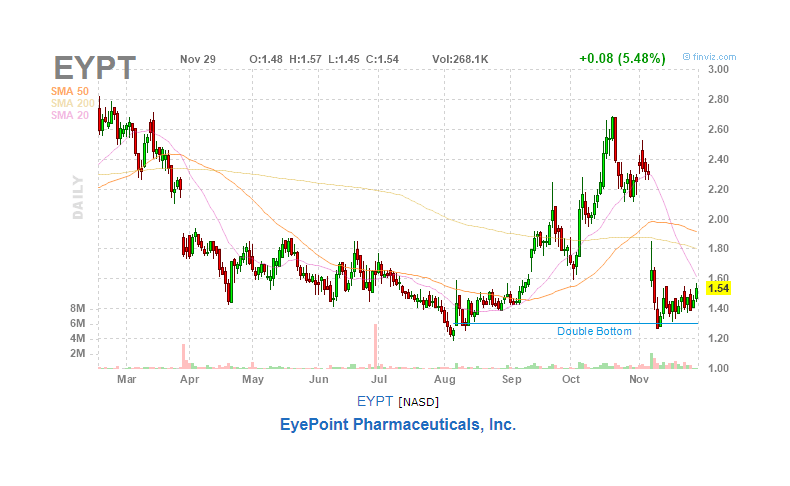
These small-cap growth stocks that are in the first inning of their growth trajectory can be extremely volatile as new information appears that sheds additional light on the future growth trajectory.
Even small diversions that seem insignificant in and of themselves can substantially alter the expected growth trajectory, and the Q3 figures seem to have investors marking this trajectory downwards and the likelihood of the company needing new finance upwards.
While we recognize that the shares priced in a lot, and perhaps too much of progress when they were at $2.5+, we think investors are a bit too pessimistic today, and we see room for a recovery in the share price towards $2.
By now, the main reason for the disappointment should be well-known, which is the sharp divergence of revenue growth from the underlying customer acceptance.
 Data by YCharts
The above figure is surprising at first sight. After having introduced two new promising products (YUTIQ and DEXYCU, which we discussed in our previous article) into the market and sales taking off in Q2 to $7.2 million, they have fallen back sharply in Q3 to just $2.5 million.

