
Summary
- I've received a few questions regarding CVS Health following the latest surge in share prices and whether I've changed my stance from bullish.
- CVS currently trades at just around 10 times earnings. Compared to historical averages and future expectations, this is still lowball.
- My bullish stance remains - albeit somewhat moderated - and the third-quarter results cement my overall positive thesis on the company as a long-term holding.
CVS Health (CVS) has thus far been an excellent exercise that one can do when a strong company becomes fundamentally undervalued in the light of potential forward risks and starts trading as though these risks have become a reality. That was the case and the article language in the case of the company. Many argued as though Amazon (NASDAQ:AMZN) had already established a dominant market presence, or as though the company's holdings were essentially worthless.
People are slowly waking up to what CVS actually is - and after a third-quarter earnings/revenue beat, the stock has recovered some ground. It's hard to believe that only a few months back, you could acquire this giant at a YOC of ~3.4%, looking at the current ~2.7% dividend yield.
Let's take a look at 3Q19 and see where we are in terms of valuation.

3Q19 was excellent
No doubt about it. The company had an excellent 3Q19, coming in at an EPS well above the highest-end range of the guidance. Here are some other highlights:
- Strong operating performance across the company, with outperformance in Health Care Benefits and in-line performance from Retail/LTC and Pharmacy Services.
- 37% revenue and significant script expansion outpacing overall marketing; 1.1% increase to 26.6% of retail script share for the company.
- Raising the EPS guidance range for FY19 from $6.89-7.00 to $6.97-7.05.
- $0.2/share in capital gains recorded YTD, with a 166.9% increase in operating cash flow. Despite this, maintenance CapEx has not significantly increased in the same vein during the same nine months.
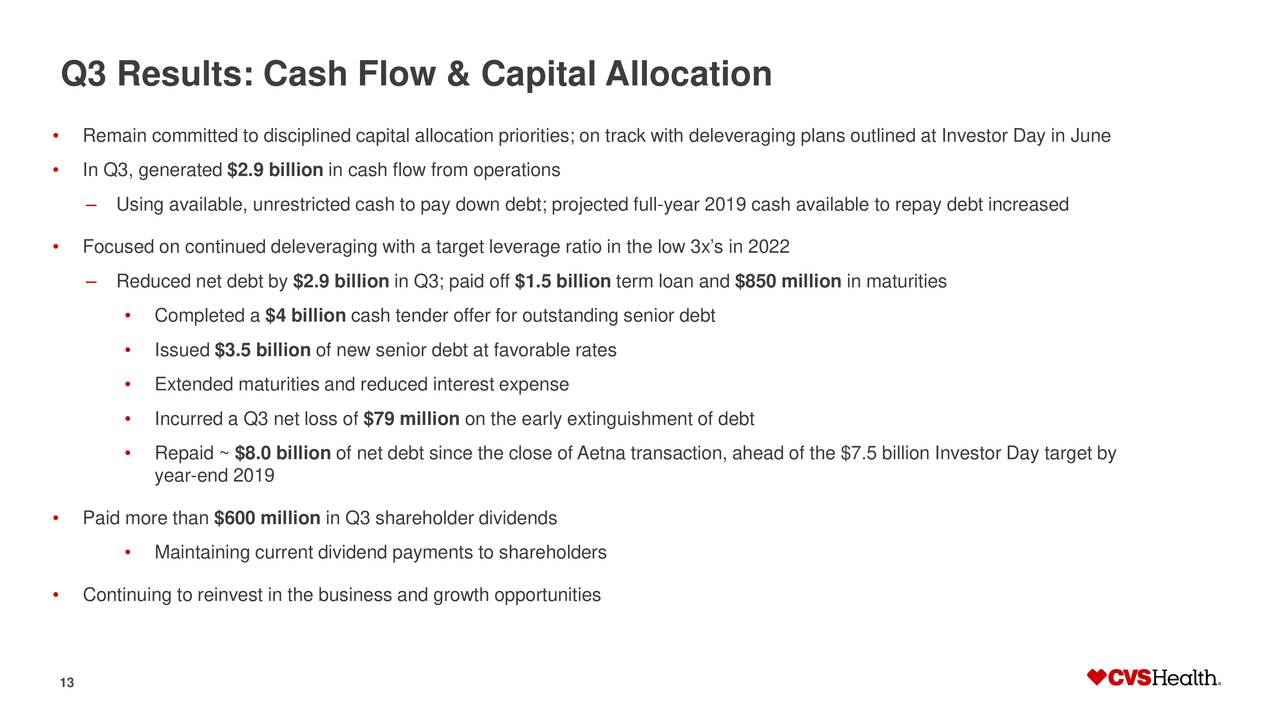
Company cash flow has more positives.
(Source: CVS Earnings Call Presentation)
Among the highlights is the continued downpayment of debt, which is improving the company's interest expenses and leverage.
On the execution side, when looking at the company's HealthHUBs, which are starting up (in Houston), these projects are showing outperformance over time (8M) compared to the control group through higher script volume and clinic visits as well as higher store sales, traffic, and margins.
While some of these effects may be geographical - such as part of traffic - the overall picture is that these things are paying off through enhanced services and offerings.
The company is targeting to open up to 1,500 HUBs over the next year and more, boosted by these initial effects as well as the recognition from the industry as a whole. CVS MinuteClinic received Pathway for Excellence designation from the American Nurses Credentialing Center. It may be viewed as fluff, but MinuteClinic is the first-ever retail clinic to receive this designation.

