
Akamai Technologies (AKAM) is taking another leg lower today, 7/26, after the company's Q2 results and Q3 guide disappointed investors. The stock is now down 31% YTD. Although the company's operating results are deteriorating (margin compression is causing earnings to fall), the stock is now getting too cheap to ignore. We believe the company will revamp its revenue growth story as OTT offerings become more robust. This revamped revenue growth will push margins higher, and earnings growth will resume a normal upwards trajectory from this year's depressed base. Consequently, we think the stock can head materially higher from these levels.
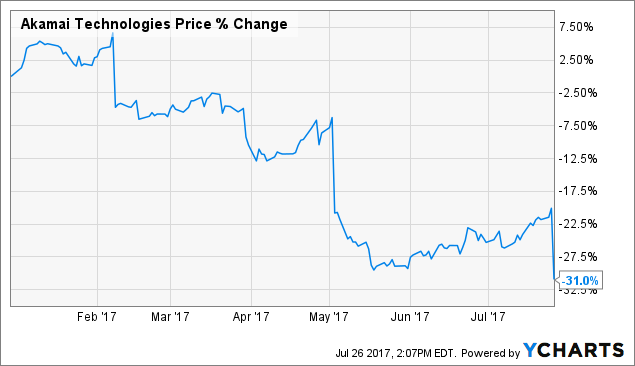 AKAM data by YCharts
The quarter was more of the same stuff AKAM investors have been hearing for some time. Most of the business is progressing just fine. Performance and Security Solutions revenue rose 16% year-over-year to $376 million. Cloud Security Solutions revenue rose 34% year-over-year to $115 million. Services and Support Solutions revenue rose 13% year-over-year to $54 million.

