
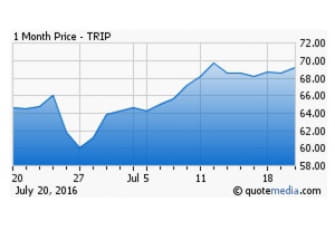
TripAdvisor (NASDAQ:TRIP) has been climbing steadily since its YTD trough in February. This begs the question - is there more room to grow? From my research, I find that the consensus view has a rosy outlook on the adoption of Instant Booking (aka. IB), mobile usage and the non-hotel segment. I see 3 factors leading the stock price lower: 1) revenue being pressured as a result of limited growth on the user side and commission per click (aka. CPC); 2) new, highly anticipated initiatives such as IB and growth of Other segments stall; and 3) premium valuation turns more in line with the industry norm.
Industry Outlook & Current Market Dynamics
Gathering data from a number of sources such as eMarketer and Phocuswrightand making my own estimates, I built a TAM Analysis on the online travel industry. Online travel spending is expected to grow worldwide and U.S.'s contribution to the global market is also expected to tilt higher. Excluding the corporate travelers, whose market is dominated by Amex and Concur, I project a 7% CAGR in global consumer online travel spending that TRIP may benefit from.
READ FULL ARTICLE HERE

